At a time when higher interest rates and tight capital have made affordable housing finance harder to secure, The Community Development Trust (CDT) is leaning into the structure that has long set it apart. The private REIT and certified community development financial institution operates both debt and equity platforms, allowing it to finance new construction, acquire existing affordable communities, and draw income from different parts of the capital stack while achieving mission outcomes.
That hybrid model has become especially valuable in 2026. CDT is originating what it describes as very strong debt volume, selectively adding properties to its equity portfolio, and strengthening its balance sheet after completing a $50 million capital raise. The organization currently has about $3 billion under management in debt and equity capital across properties in 45 states and regions, supporting more than 33,000 affordable homes and 115,000 residents.
“We pursue both mission and returns on our capital,” says Michael Lear, CDT’s chief business development officer. “All of our investments are intended to produce mission outcomes for residents while providing strong risk-adjusted returns to our investors.”
CDT has pursued that double-bottom-line mandate for 28 years, but Lear notes the current market puts a premium on long-term capital, disciplined underwriting, and a diversified investment base.
Filling a Lending Gap
CDT’s debt business has accelerated as higher rates have reshaped lender competition. Smaller affordable housing loans remain a particular focus.
The REIT primarily provides long-term permanent financing for developments using either 9% or 4% Low-Income Housing Tax Credits (LIHTC). Many of the projects are new construction. CDT typically makes a forward commitment before a building is completed, then funds the permanent loan after construction is finished, occupancy has stabilized, and the property satisfies the conversion requirements.
Demand is particularly strong in the $4 million to $7 million loan range. CDT originates loans directly and works with correspondent lenders. Each transaction must create or preserve housing for lower-income households. The typical terms of the loans are over 15 years.
“We remain focused on this business because it is a core business to us,” says Christopher Blair, CDT’s chief product officer and treasurer. “In the current market, we are filling a gap that is not particularly well served by other capital sources, and we are seeing significant demand for CDT’s debt products.”
The loans also serve a corporate purpose. Long-term mortgages on stabilized, income-restricted properties provide predictable cash flow that can temper the risks inherent in equity ownership and preserve flexibility for future lending and equity commitments.
“The quality and stability of the income from the debt portfolio cannot be understated from a corporate perspective,” Blair says. “We have found these assets perform consistently well over the long run and across cycles.”
The platforms do not have to participate in the same transaction to reinforce one another. Debt investments add stable income and support liquidity, while equity ownership offers long-term value growth and more direct influence over property operations. Together, they diversify cash flow across the balance sheet and allow CDT to keep pursuing its mission when one side of the market offers more activity than the other. The hybrid design also distinguishes CDT from equity-only REITs and mortgage-only lenders.
Selective Equity in Strong Markets
On the equity side, CDT generally serves as the majority limited partner in joint ventures with affordable housing operators. Its partners source acquisitions and oversee operations, while CDT supplies capital and helps shape the business plan and long-term preservation strategy.
Most properties serve households earning no more than 60% of area median income. They generally have project-based Section 8 contracts or long-term affordability restrictions tied to LIHTCs.
Geography matters less than the rental market and the rent advantage. CDT looks for communities where restricted rents sit meaningfully below comparable market rents, supporting consistent demand while providing residents with more affordable rents. It also favors sound assets that can be substantially capitalized and financed with long-term, fixed-rate debt.
That rent advantage is also an underwriting buffer. In supply-constrained markets, it supports occupancy and reduces the likelihood that residents will leave for competing units, while fixed-rate financing limits exposure to future interest-rate swings. Those characteristics can help stabilize cash flow across the holding period.
“We are cautious in a time of volatility and when absorbing equity risk,” Lear says. “But we have found attractive opportunities with high-quality, aligned operating partners, and assets we believe in for the long run.”
That discipline also determines which opportunities CDT rejects. Affordable status by itself is not always sufficient if the restricted rents offer little or no savings from market rents. The company wants a measurable economic benefit for residents, a durable revenue profile, and a partner prepared to protect both over a holding period that commonly exceeds 10 years.
“We want to invest in affordable housing that provides real, measurable affordability,” says Grace Cheng, CDT’s COO and CFO. “The same features that make the assets attractive from an operating perspective align with the underlying mission reasons for what we do.”
Preserving Affordability in High-Cost Markets
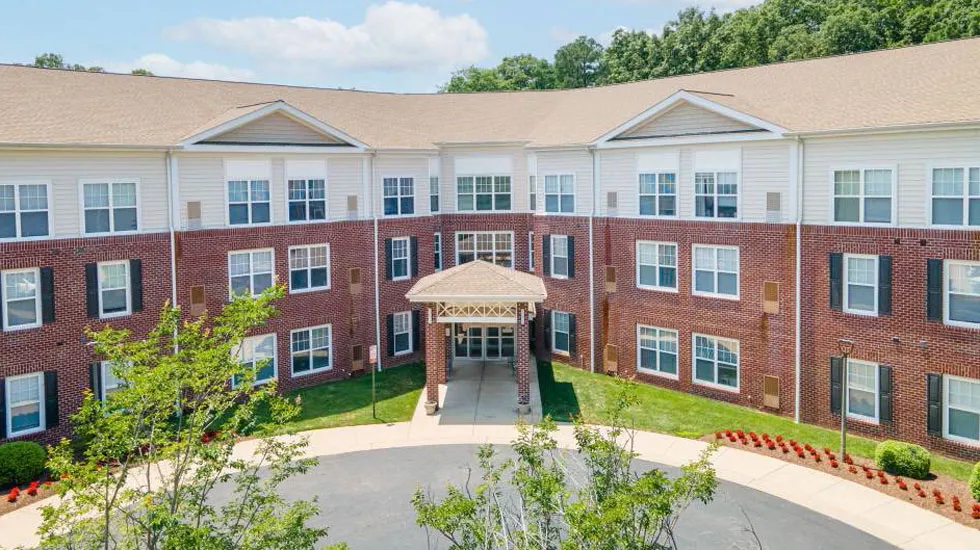
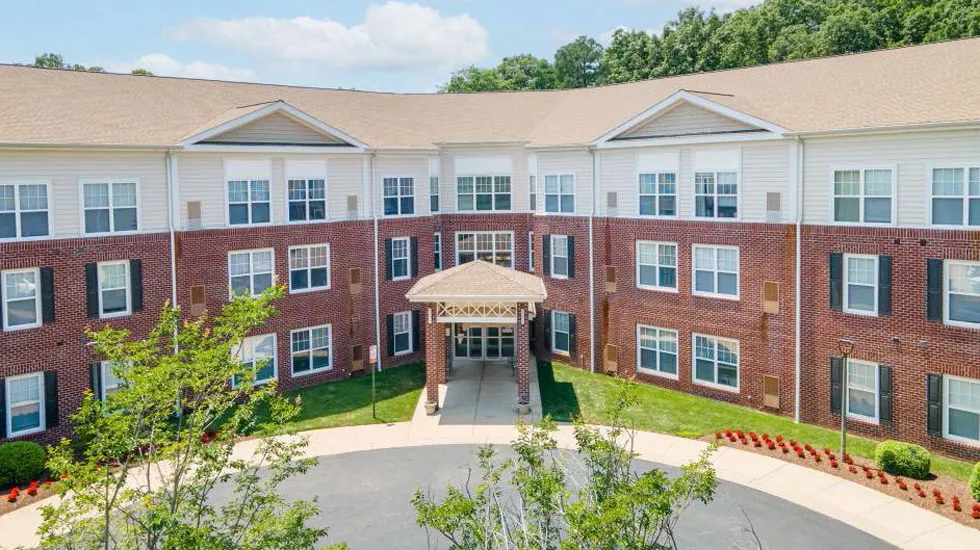
That approach is reflected in Atlantic at Twin Hickory, a 110-unit age-restricted community in Glen Allen, Virginia, that CDT acquired with affordable housing investment firm Liam Moor. The property serves residents earning no more than 60% of area median income under the senior LIHTC program. Its rents are hundreds of dollars below those of comparable market-rate housing in an area of the Richmond metropolitan region where affordable senior options are limited.
The transaction was CDT’s first with Liam Moor. The companies found common ground on financial and mission objectives. Liam Moor sourced the deal and oversees operations, while CDT contributed the majority of the equity.
“We bring the equity capital, but we also bring an intentional ethos about what we want our capital invested in and with whom,” Lear says. “We are very selective about our operating partners because we take such a long-term and reputational view.”
Atlantic at Twin Hickory is in the later phase of its original tax-credit restrictions. CDT plans to hold the property, maintain its condition, and work with public partners to extend its affordability. Lear says the previous owner maintained the community responsibly, giving the new venture a strong starting point.
“It is one thing to buy these properties,” Lear says. “It is another to think holistically about the life cycle of the property, its residents, and the asset itself.”
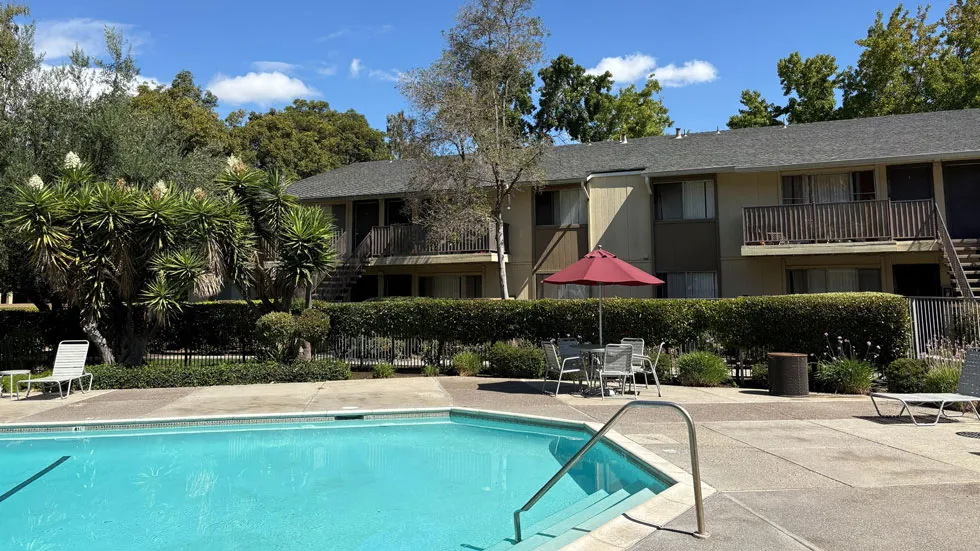
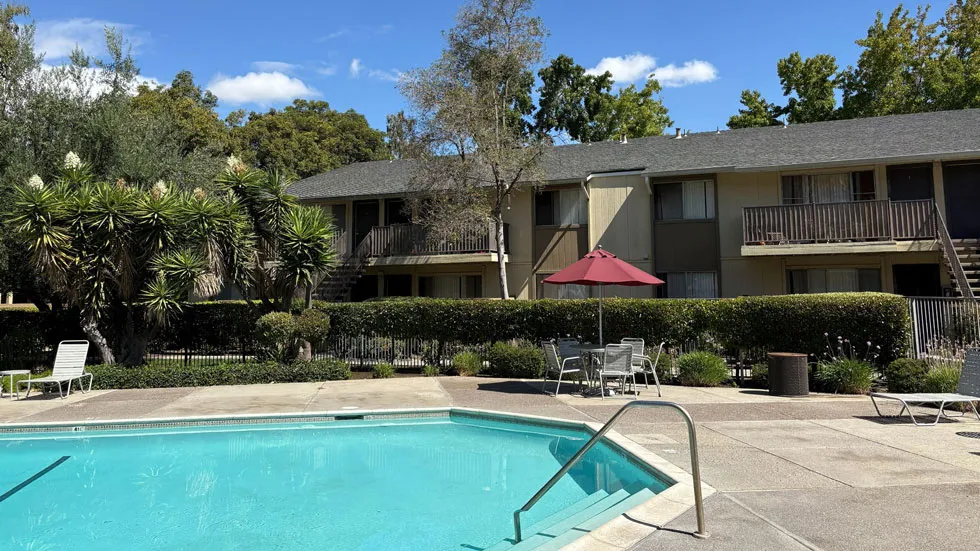
CDT also made its first Bay Area equity investment with the acquisition of Almaden 1930 Apartments in San Jose. The 151-unit community serves households earning between 50% and 60% of area median income in one of the country’s most expensive and supply-constrained rental markets. The transaction extended the property’s affordability restrictions through 2072 and included a Freddie Mac Preservation Rehab loan.
“The mission is baked into its existence,” Lear says. “The question is how you capitalize the asset so that you continue to provide quality affordable housing.”
Despite San Jose’s high acquisition costs, CDT saw an opportunity to invest more in the property than another buyer might have committed. The capital will protect the building and resident experience while keeping rents hundreds of dollars below those of comparable market units.
A third 2026 acquisition involved a project-based Section 8 community west of Boston. Lear says it follows the same formula: a quality asset in a strong market where affordability benefits residents and reduces revenue risk.
Capital to Act When Others Pull Back
CDT’s ability to pursue those investments was reinforced by a $50 million Series F raise in 2026, bringing capital raised since its founding to more than $420 million. Its investors have historically included banks and insurance companies drawn to long-duration investments.
“We tend to raise capital when we do not need it,” Cheng says. “We were successful in raising long-term, accretive capital in an environment that has been challenging for many others.”
Along with committed credit lines and other liquidity, the raise allows CDT to wait for investments that meet its standards instead of relaxing them to keep money moving.
The new capital supports both sides of the hybrid platform and gives CDT flexibility to manage its existing portfolio. The debt business can continue meeting demand for smaller permanent loans, while the equity team can capitalize properties adequately at closing and absorb future needs without relying on a favorable refinancing window.
Measuring the Resident Impact
CDT measures impact through household incomes, rent savings, and resident stability. Its 2026 impact report says 48% of units are affordable at or below 50% of area median income and 80% at or below 60%. Portfolio occupancy stands at 94%.
The report estimates that residents save an average of $137 a month for a one-bedroom apartment and $180 for a two-bedroom apartment compared with market rents. The savings rise to $297 for a three-bedroom and $619 for a four-bedroom home. Those amounts can be redirected to food, transportation, health care, and other household expenses.
Long-term ownership is harder to reduce to a single figure, but it is central to CDT’s mission. Frequent sales can create management disruptions and tie capital improvements to financing cycles. An investor expecting to remain for a decade or longer has a different incentive to address major building systems before they fail.
“If someone plans to own a property for three years, they may not replace a roof that will need to be replaced in four,” Lear says. “When we intend to own a property for 10 years or more, we are going to replace that roof.”
CDT reports that 51% of residents have lived in their apartments for at least five years, compared with a national renter average of 36%. That continuity can keep adults near their jobs and children in the same schools while supporting dependable property cash flow.
Continuity and the Next Cycle
CDT added continuity at the board level in July by naming Brian Hudson, Sr. as chair. A director for several years, Hudson brings experience in housing policy and affordable housing finance at the local, state, and federal levels.
“CDT’s complimentary portfolios have proven to be quite stable over the years,” Hudson says. “Given the strength of our balance sheet, we’re optimistic about collaborating with our partners to create and preserve affordable housing across the country in this challenging economic environment.”
Looking toward 2027, CDT expects demand for its permanent lending products to remain strong. CDT will continue to evaluate mission-centered equity investments with existing and prospective operating partners. Management’s priorities remain adding stable debt assets, acquiring core affordable communities, and protecting liquidity for periods when market dislocation produces favorable openings.
“We have been resilient through multiple cycles and benefit from a diversity of cash flows across our debt and equity businesses,” Lear says. “In a time of uncertainty, continuing to strengthen that model is the best thing we can do to serve the future of the company.”